
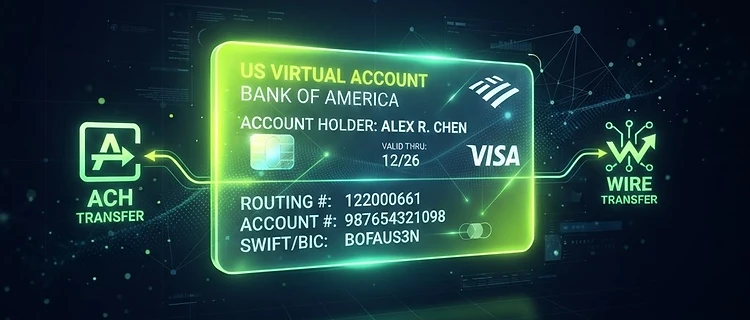
Virtual USD Account: Receive International Dollar Payments Without a US Bank
A virtual USD account gives you a US routing and account number to receive dollar payments from anywhere — without a US bank, a US entity, or visiting the US. Learn how it works and how to get one.
Virtual USD Account: Receive International Dollar Payments Without a US Bank
A virtual USD account gives you a US routing number and account number in your name, so you can receive US dollar payments via ACH and Wire from anywhere in the world — without opening a US bank account, forming a US company, or stepping foot in the United States.
This guide explains what a virtual USD account is, how it works, and how to use one to receive international payments.
What Is a Virtual USD Account?
A virtual USD account is a dollar-denominated account issued by a regulated financial infrastructure provider (not a traditional bank) that gives you standard US banking credentials:
- A routing number (9 digits, identifies the receiving bank)
- An account number (identifies your account)
- A beneficiary name (your name or company)
- A bank name and address (for wire instructions)
From a sender's perspective, sending money to a virtual USD account is identical to sending to any US bank account. They enter the routing and account number in their banking app and the funds arrive.
Who Needs a Virtual USD Account?
- Freelancers outside the US paid by US clients
- Remote workers employed by US companies
- Agencies invoicing US-based clients
- Exporters selling goods to US buyers
- SaaS founders collecting USD subscriptions
- Anyone who invoices in dollars but can't open a US bank account
How It Works
- Register on a platform that issues virtual USD accounts (FinT365, powered by Bridge).
- Complete identity verification (KYC for individuals, KYB for businesses).
- Get approved — KYC takes under a minute; KYB usually same day.
- Open a USD account — receive your routing and account number.
- Share your details with clients or employers.
- Receive payments via ACH (domestic US) or Wire (international SWIFT).
Virtual USD Account vs. Traditional US Bank Account
| Feature | Traditional US bank | Virtual USD account | |---|---|---| | US entity needed | Yes | No | | US address needed | Yes | No | | In-person visit | Often | Never | | Time to open | Weeks | Minutes to days | | Receives ACH | Yes | Yes | | Receives Wire/SWIFT | Yes | Yes | | Monthly fees | Common | Usually $0 | | Converts to crypto | No | Often yes |
The Hidden Advantage: Automatic Conversion
The biggest benefit of a modern virtual USD account isn't just receiving dollars — it's what you can do with them next. Platforms like FinT365 let you connect a crypto wallet and automatically convert every incoming dollar payment to USDC or USDT stablecoins, sent directly to your wallet.
This means:
- No manual exchange steps
- No leaving money on a crypto exchange
- No spread or hidden FX markup
- Stablecoins in your self-custody wallet within minutes of settlement
Receiving Payments
ACH (domestic US)
Used when the sender has a US bank account. Free for the sender, settles in 1–2 business days. Ideal for US clients paying US-based invoices.
Wire / SWIFT (international)
Used for international transfers. The sender's bank charges a SWIFT fee (typically $15–$40). Settles in 1–5 business days. Ideal for non-US clients paying in dollars.
What You Need to Open One
For individuals (KYC)
- Government-issued ID (passport, driver's license, or national ID)
- Selfie / liveness check
- Proof of address (sometimes)
For businesses (KYB)
- Company registration documents
- Business tax ID
- Beneficial owner information
- Registered business address
- Proof of address
The verification is mandatory and a sign of a legitimate platform. Any "virtual account" that skips verification will eventually freeze your funds.
Supported Currencies Beyond USD
A good virtual account platform supports multiple currencies, not just USD:
- USD — ACH / Wire
- EUR — SEPA
- GBP — FPS (Faster Payments)
- MXN — SPEI
- BRL — PIX
This lets you invoice in the currency your client prefers and still receive in your chosen stablecoin.
FAQ
Do I need a US bank account? No. A virtual USD account gives you US banking credentials without a US bank.
Do I need a US company? No. You can open a virtual USD account as an individual or a non-US company.
How fast do payments arrive? ACH settles in 1–2 business days. Wire/SWIFT in 1–5 business days. Once settled, conversion to stablecoins happens within minutes.
Can I receive from any country? Most countries are supported, subject to KYC/KYB approval. Sanctioned jurisdictions are excluded.
Can I convert to crypto? Yes — on FinT365, set a crypto wallet as your destination and every payment auto-converts to USDC or USDT.
Summary
A virtual USD account gives you a US banking identity — routing number, account number, ACH and Wire — without a US bank, a US entity, or an in-person visit. For anyone who invoices in dollars but lives outside the US, it's the fastest, cheapest way to get paid. And when paired with automatic conversion, every dollar arrives as stablecoins in your own wallet.