US USD Account: Deposit Dollars and Withdraw USDC (2026 Guide)
Open a US USD account online, receive ACH and wire payments, then withdraw your balance as USDC or send transfers worldwide — with no monthly fee and no minimum balance.
Ready to get paid in stablecoins?
Open your FinT365 account — receive fiat from clients worldwide and auto-convert to USDC/USDT.
US USD Account: Deposit Dollars and Withdraw USDC (2026 Guide)
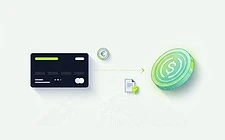
For most people outside the United States, the problem was never earning dollars — it was receiving them. A US USD account with stablecoin payouts solves that in one step: you get real American account details that domestic payers can send ACH and wire payments to, and you withdraw the balance as USDC on-chain, or send it on as an international transfer.
This guide walks through both directions — dollars in, stablecoins out.
What is a US USD account?
A US USD account gives you the details an American payer expects: a routing number and account number, in your own name, usable for ACH transfers and domestic wires. It behaves like a normal US checking account from the payer's point of view — no international wire, no correspondent bank, no surprise fees on their side.
With FinT365 you open one online in minutes and get:
- USD account details — routing and account number for ACH and wire
- GBP account details — sort code and account number for Faster Payments and BACS
- EUR account details — IBAN and BIC for SEPA
- No monthly fee and no minimum balance requirement
- Automatic conversion of incoming dollars into USDC or USDT on Ethereum, Solana, Polygon, Base or Arbitrum
- International transfers out to bank accounts in 30+ currencies
Account details, payment rails and identity verification are provided through our regulated payment provider. FinT365 is the software layer that connects them.
The advantages: why a USD account with USDC payout beats a traditional US business account
1. No monthly fee and no minimum balance
Traditional US business checking accounts charge a monthly maintenance fee unless you keep a balance above a threshold — often $1,500 to $5,000. Here there is no monthly fee and no minimum. Money sits in the account free of charge until you choose to move it.
2. No US address, no US entity required
You do not need a US company, a US phone number or a US address to hold dollar details. You get routing and account numbers that work with domestic ACH — which means your client's payment does not become an expensive international wire.
3. Instant settlement to USDC
Dollars convert to USDC the moment a payment is credited, automatically, at your chosen percentage. There is no waiting period and no need to route funds through an exchange.
4. One balance, five rails, thirty currencies
USD, GBP, EUR, MXN and BRL details from a single account, with international transfers out to 30+ currencies. You stop maintaining a collection of accounts in different countries.
5. Transparent pricing
A single published conversion fee instead of a hidden FX spread. You can see exactly what a payment costs before you move it.
How to deposit dollars into your US USD account
Once your account is open, you can receive money through the standard US rails:
Share your routing number and account number exactly as they appear in the dashboard, and always include your payment reference. The reference is how an incoming payment is matched to your account automatically.
Tip: ask US clients to send ACH rather than an international wire. ACH is typically free or near-free for them and arrives in a fraction of the time.
How to withdraw USDC from your USD account
There are two ways to take value out, and you can combine them.
Option A — Automatic conversion (recommended)
Enable auto-conversion and every incoming dollar is converted to your chosen stablecoin at the percentage you set — up to 100%. Choose the asset (USDC or USDT) and the network once, and every future payment follows the same rule.
Option B — Manual withdrawal
Keep the balance in dollars and convert whenever you decide. Useful when you are holding dollars for supplier payments and only want to move the surplus.
What you choose when you withdraw:
- Asset — USDC or USDT
- Network — Ethereum, Solana, Polygon, Base or Arbitrum
- Destination address — an external wallet you control, or a wallet held in your FinT365 account
Make sure the network you pick is the one your destination wallet supports. USDC sent on Base will not arrive at an address that only accepts Ethereum.
Step by step: dollars in, USDC out
- Open your account and complete verification. Individual verification is usually under a minute; business verification is typically the same business day.
- Add your destination wallet — paste the address and select its network.
- Set your conversion rule — percentage to convert, asset and network. 100% if you want everything in stablecoins.
- Send your USD details to the payer — routing number, account number and the payment reference.
- Watch it land — the payment appears in your dashboard, converts, and the on-chain transfer is created with a transaction hash you can verify yourself.
US USD account vs a traditional US business checking account
Who is this for?
- Freelancers and contractors worldwide whose clients pay in dollars
- US LLC owners who want their income in stablecoins rather than sitting in a bank
- Agencies and consultancies invoicing US clients in USD
- Marketplace and app sellers receiving US platform payouts
- Crypto-native businesses that want fiat income converted the moment it arrives
If you are evaluating the full product first, read Free Business Checking Account USA and Virtual USD Account: Receive International Dollar Payments.
FAQ
Is FinT365 a bank?
No. FinT365 is a software platform. The account, the payment rails and identity verification are provided through our regulated payment provider. You get real US account details and regulated infrastructure — without the overhead of a traditional bank relationship.
Do I need a US company to open a USD account?
No. Businesses and individuals outside the United States can hold USD account details. Availability depends on your country of residence, which is confirmed during verification.
How fast do USD deposits arrive?
ACH payments typically settle in one to three business days, same-day ACH within the business day, and domestic wires the same day. Your dashboard shows every incoming payment as soon as it is matched to your reference.
Can I withdraw USDC and still keep dollars in the account?
Yes. Set your conversion percentage below 100% — for example 30% — and only that share of each incoming payment is converted. The remainder stays as dollars.
Which networks are supported for USDC withdrawal?
Ethereum, Solana, Polygon, Base and Arbitrum. USDT is supported on the same set of networks.
Is there a monthly fee or minimum balance?
Neither. There is no monthly account fee and no minimum balance. You pay only when you convert or move money.
The bottom line
A US USD account with USDC payout gives you the one thing that used to require an American company and an American bank: real dollar account details that domestic payers can send ACH and wires to.
From there you decide what happens next — leave the balance in dollars, convert it automatically to USDC, or send it on as an international transfer in one of 30+ currencies. No monthly fee, no minimum balance, no US entity required.
Ready to receive your first dollar? Open your free multi-currency account and add your USDC wallet in minutes.
Start receiving international payments today
Open a multi-currency account in minutes. Get paid by clients worldwide and auto-convert every payment to stablecoins — only on FinT365.
No credit card required · KYC takes under a minute