Business Checking Account in 2026: Why Traditional Banks Are Falling Behind
Traditional business checking accounts were built for a pre-crypto world. This comparison explains what's changed, why traditional banks can't keep up with crypto-integrated accounts, and what your business should look for instead.
Ready to get paid in stablecoins?
Open your FinT365 account — receive fiat from clients worldwide and auto-convert to USDC/USDT.
Business Checking Account in 2026: Why Traditional Banks Are Falling Behind
The business checking account hasn't meaningfully changed in fifty years. You deposit fiat, you hold fiat, you transfer fiat, and you pay monthly fees for the privilege. Meanwhile, the financial world around the bank account has been transformed by stablecoins, instant settlement, and self-custody. This guide explains why traditional business checking is falling behind — and what to look for in a modern alternative.
What a Traditional Business Checking Account Does Well
Let's be fair: traditional bank accounts do some things well.
- Regulatory trust — FDIC insurance, established institutions
- Fiat rails — ACH, Wire, SEPA, SWIFT all work
- Integration — accounting software, payroll, tax reporting
- Physical presence — branch access, in-person services
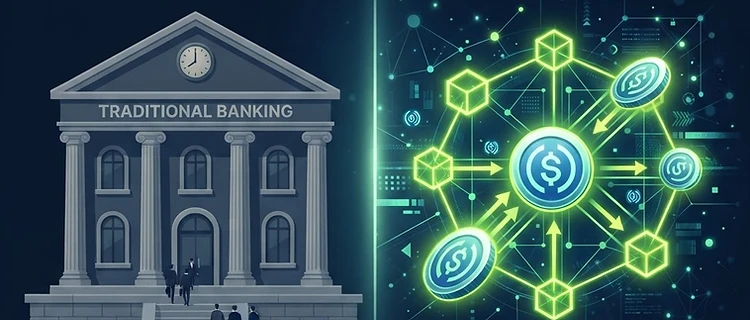
These things matter. The problem isn't that traditional accounts are broken — it's that they stop exactly where modern business needs begin.
Where Traditional Business Checking Falls Behind
1. No native crypto integration
A traditional bank account holds fiat. If your business needs stablecoins — to pay contractors, hold treasury, or settle on-chain — you manually move money to an exchange, buy crypto, withdraw it, and pay fees at every step. A crypto-integrated account does all of this automatically.
2. Geographic restrictions
Opening a USD business account at a US bank typically requires a US entity and US address. A virtual USD account does not — and works just as well for receiving ACH and Wire.
3. Slow onboarding
Traditional bank onboarding takes weeks. A virtual account, after KYB, opens in minutes.
4. Fees for holding money
Traditional business checking charges $10–$50+/month just to hold your money. Modern virtual accounts are usually $0/month with no minimum balance.
5. No self-custody delivery
A bank controls your funds. A crypto-integrated account sends stablecoins to your wallet — you control the keys.
6. Closed on weekends and after hours
Bank wires stop. Blockchains run 24/7.
Traditional Business Checking vs. Crypto-Integrated Checking
What This Means for Your Business
If your business:
- Invoices in USD but isn't a US company
- Pays contractors or suppliers in crypto
- Wants treasury in stablecoins
- Operates across borders
- Values speed and self-custody
…then a traditional business checking account is the wrong default. You don't need to close your bank account — you need a complementary account that handles the parts your bank can't.
The Hybrid Setup Most Businesses Use
- Keep a traditional bank for payroll, tax, and local fiat needs.
- Add a virtual multi-currency account for receiving international payments.
- Enable automatic conversion to send stablecoins to your treasury wallet.
- Use the stablecoin wallet to pay crypto-native contractors and on-chain expenses.
This split gives you the regulatory trust of a bank where it matters and the speed and self-custody of crypto where it matters.
What to Look for in a Modern Business Checking Alternative
- Proper KYB — real verification is a feature, not a bug. No-KYC accounts get shut down.
- Multi-currency — USD, EUR, GBP at minimum, ideally MXN and BRL too.
- Automatic conversion — not manual buying. Set it once, forget it.
- Self-custody delivery — stablecoins to your wallet, not the platform's custody.
- Transparent fees — one per-conversion fee, no hidden spread.
- Regulated infrastructure — the underlying provider should be regulated (FinT365 uses Bridge).
FAQ
Should I close my traditional bank account? No. Keep it for payroll, taxes, and local fiat. Add a crypto-integrated account for international receipts and on-chain treasury.
Are virtual accounts as safe as a bank? Funds in virtual accounts are handled by regulated infrastructure providers. While held at the partner bank, FDIC insurance applies. The key difference is what happens after — automatic conversion to self-custody stablecoins, which a bank can't offer.
Why do traditional banks charge monthly fees? Legacy cost structures: branch networks, compliance overhead, minimum balance requirements. Virtual accounts have lower cost structures and pass that on as $0 monthly fees.
Summary
Traditional business checking accounts still do the basics well — but they stop at fiat. For businesses that operate across borders and across the fiat/crypto divide, a crypto-integrated virtual account is no longer optional. You don't need to replace your bank — you need to complete it.
Start receiving international payments today
Open a multi-currency account in minutes. Get paid by clients worldwide and auto-convert every payment to stablecoins — only on FinT365.
No credit card required · KYC takes under a minute