Business Checking Account with Stablecoin: The Complete 2026 Guide
A business checking account that settles incoming payments into stablecoins isn't a future concept — it's live in 2026. This guide explains how stablecoin-native business checking works, who it's for, and how it compares to traditional business accounts.
Ready to get paid in stablecoins?
Open your FinT365 account — receive fiat from clients worldwide and auto-convert to USDC/USDT.
Business Checking Account with Stablecoin: The Complete 2026 Guide
A business checking account has one core job: receive payments from clients and make them usable fast. For decades, "usable" meant "sitting in a bank balance." In 2026, for an increasing number of businesses, "usable" means sitting in stablecoins in your own wallet — ready for DeFi, ready for crypto-native suppliers, ready to move globally in minutes.
This guide explains how a stablecoin-native business checking account works, who it's for, and how it changes the math on fees, speed, and custody.
What is a stablecoin-native business checking account?
A traditional business checking account:
- Client sends fiat → lands in your bank account
- Fiat sits in bank balance (or you manually move it)
- To get crypto: withdraw → exchange → swap → wallet (4 steps, 4 fees)
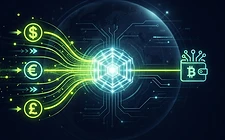
A stablecoin-native business checking account (like FinT365):
- Client sends fiat → lands in your virtual account
- Auto-converts to USDC/USDT on arrival
- Settles to your own crypto wallet in minutes
The fiat step still happens — clients pay in USD, EUR, GBP — but the conversion is automatic and the destination is your wallet, not a custodial balance.
Why businesses are switching in 2026
1. Lower total fees
Traditional path (fiat → crypto) stacks fees:
- Bank FX markup (1–3%)
- Bank withdrawal fee ($15–$50 for international)
- Exchange spread (0.1–1%)
- On-chain withdrawal gas ($3–$20)
A stablecoin-native account collapses that to a single transparent % on the conversion. For a business processing $50K/month in international payments, that's hundreds of dollars saved.
2. Minutes, not days
A bank-to-exchange-to-wallet flow takes 2–5 business days. A stablecoin-native account settles in minutes after the fiat lands. For businesses that need to pay suppliers, move treasury, or deploy into DeFi quickly, this is a structural advantage.
3. Self-custody by default
When funds sit in a traditional bank, the bank can freeze them — and does, during compliance reviews, disputes, or policy changes. When funds auto-route to your own non-custodial wallet, no platform can freeze them. For businesses operating in jurisdictions with unpredictable banking, this is risk management, not just a feature.
4. Chain choice for cost control
A stablecoin-native account lets you pick the settlement chain. A $500 payment settling on Polygon or Base costs fractions of a cent in gas; the same payment on Ethereum mainnet might cost $3–$8. You choose per-account based on what you're doing with the funds.
5. Crypto-native supplier payments
If your suppliers, contractors, or service providers prefer stablecoins (and in 2026, many do), settling directly into USDC means you can pay them without routing back through a bank. The whole cash loop stays on-chain.
Who is a stablecoin business account for?
- Crypto-native startups — treasury in stablecoins, fiat inbound for client payments
- Web3 agencies & studios — bill clients in fiat, keep treasury in stablecoins
- Export businesses in emerging markets — avoid local currency depreciation, settle in USD-pegged stablecoins
- Freelance collectives & DAOs — distribute payments in stablecoins
- Any business paying crypto-native suppliers — skip the fiat round-trip
Who should NOT use one
- Businesses that need a USD balance for payroll, tax payments, or card spending (use Mercury, Novo, or a traditional bank)
- Businesses whose clients only pay in currencies outside USD/EUR/GBP/MXN/BRL
- Businesses with no crypto workflow and no interest in stablecoins
How to set one up
- Create an account on FinT365 and complete KYC/KYB (built-in via Bridge.xyz)
- Open a virtual account in the currency your clients pay in (USD, EUR, GBP, MXN, BRL)
- Set your destination — your wallet address, preferred stablecoin (USDC/USDT), and preferred chain
- Share account details with clients — they pay exactly like a normal bank transfer
- Payments auto-convert and settle to your wallet
The whole setup takes minutes to hours, not days.
Stablecoin-native vs traditional business checking
A realistic fee comparison: $20,000 client payment
Traditional bank → crypto wallet:
- Inbound SWIFT: $15–$30
- Bank FX (if non-USD): 1–2% = $200–$400
- Withdraw to exchange: $0–$25
- Exchange swap: 0.1–0.5% = $20–$100
- Wallet withdrawal gas: $3–$20
- Total: ~$240–$570, 3–5 days
FinT365 stablecoin account:
- Inbound: included
- Auto-conversion: single transparent %
- Wallet settlement: included (you pay gas, choose low-cost chain)
- Total: one fee, minutes
FAQ
Do I still need a traditional bank account? Yes, for most businesses — to pay fiat invoices, run payroll in fiat, handle taxes, and use a debit card. A stablecoin-native account complements a traditional bank; it doesn't replace it for fiat operations.
Are stablecoins safe for business treasury? USDC and USDT are the most audited and regulated stablecoins. USDC is fully backed by US Treasuries and cash (reserves attested monthly). For custody safety, the best practice is to hold in your own non-custodial wallet or a regulated custodian — not on an exchange.
Can my clients tell the difference? No. Your clients send a normal bank transfer to a normal-looking account number / IBAN / sort code. The stablecoin conversion happens on your side — transparent to them.
What happens if a payment fails or gets returned? FinT365 tracks every payment status (pending, received, converting, completed, returned). Failed conversions are surfaced in the dashboard with the Bridge.xyz error detail, so you can retry or contact support.
Which chains can I settle on? Ethereum, Solana, Polygon, Base, and Arbitrum. You set the default per-account in your conversion settings and can update it at any time.
Start receiving international payments today
Open a multi-currency account in minutes. Get paid by clients worldwide and auto-convert every payment to stablecoins — only on FinT365.
No credit card required · KYC takes under a minute